Latest News on Shakira: Not in the Headlines – A Quick Guide to Cancelling Mandatory Car Insurance
While there are no fresh updates on Shakira right now, many readers are looking for practical ways to manage their obligations. One common task in the Czech Republic is ending a compulsory auto insurance policy (“povinné ručení”). Below is a straightforward rundown of why you might want to cancel, how to do it, and what to expect.
Why Consider Terminating Your Mandatory Insurance?
- Cost savings – If you’ve sold your vehicle or are taking a long‑term break, you’ll no longer need the coverage.
- Change of circumstances – Moving abroad, switching to a different vehicle type, or opting for a different insurer can make cancellation sensible.
- Legal compliance – Ending a policy before its term ends ensures you’re not paying for coverage you’ll never use.
Step‑by‑Step How to Cancel Your Policy
Below is a simple, step‑by‑step method that mirrors the official process used by Czech insurers.
- Locate your contract number and the insurer’s contact details on your policy documents.
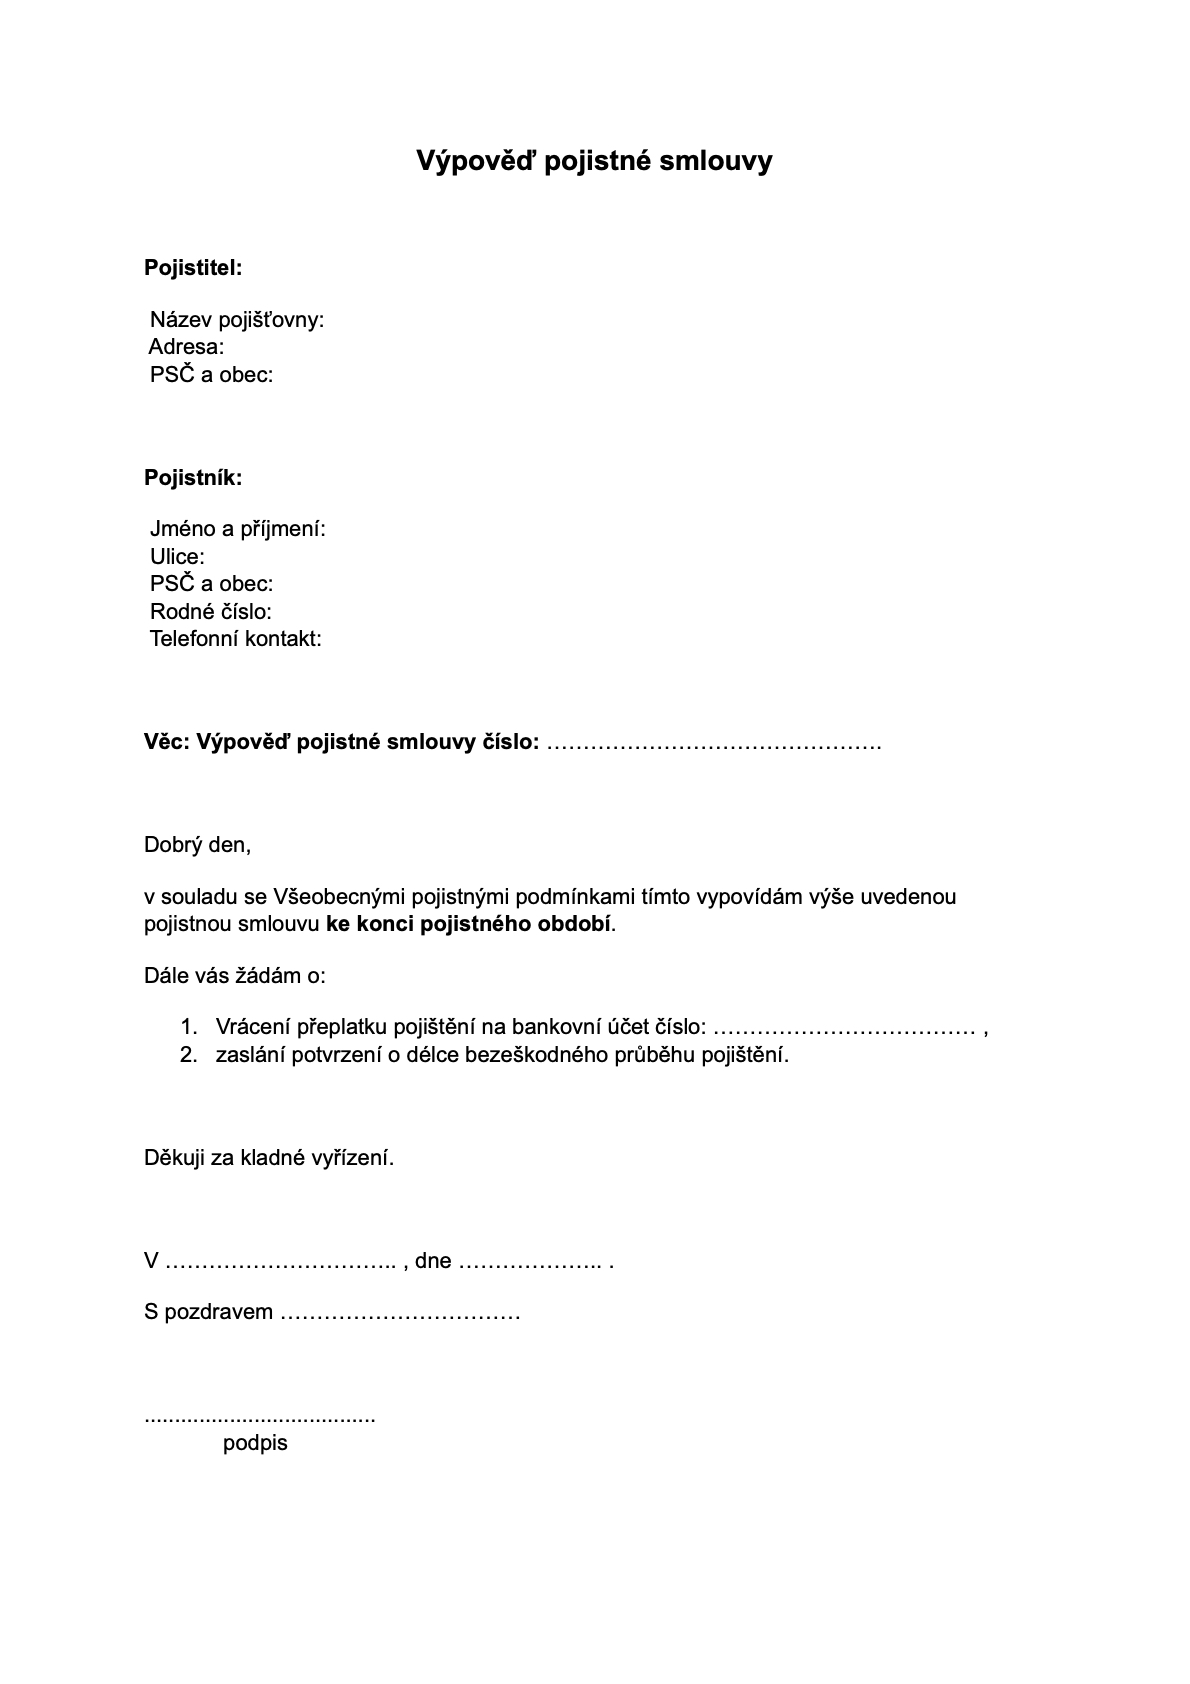
- Send a written notice of termination (výpověď). The notice can be emailed or mailed.
- State the effective date of termination – the end of the current coverage period is recommended to avoid gaps.
- Keep a copy of your notice and the insurer’s acknowledgment for your records.
- Return any unused insurance documents and request a final statement of charges.
What Happens After You Send the Notice?
- Most insurers honor the termination on the date specified. If you set the end to the current month’s last day, you’ll be covered through that point.
- You may be entitled to a refund if you paid in advance and the coverage period is not fully consumed.
- In case of an accident after the termination date, you’ll need to arrange a new policy or use a temporary cover.
Common Pitfalls to Avoid
- Missing deadlines – Late cancellations can lead to unwanted renewal or penalties.
- Assuming automatic refunds – Some insurers require a formal request or may withhold a small administrative fee.
- Overlooking additional coverage – If you have bundled services (e.g., roadside assistance), these may terminate separately.
When to Re‑Activate or Switch Providers
If you plan to resume driving, you’ll need to re‑apply for a new policy or transfer your existing coverage to a different insurer. Many companies offer online tools that compare rates, making the switch smoother.
Quick Tips for a Smooth Transition
- Check the policy end date on your contract; align your termination notice accordingly.
- Ask the insurer if they offer a refund for unused time to avoid losing money.
- Keep a digital backup of all correspondence in case of disputes.
Practical Example: A Real‑World Scenario
Jana, a resident of Prague, sold her car last month. She emailed her insurer a termination notice effective 30 days from the current policy end. Within a week, she received a refund of €120 for the unused portion. No complications arose because she followed the official steps and retained all paperwork.
Implications for Everyday Life
Terminating a compulsory policy may seem bureaucratic, but it frees up money and reduces administrative burden. If you’re traveling abroad or simply not driving, stopping the policy is a practical decision. Just remember to keep documentation, watch for any potential penalties, and be ready to reactivate coverage if you need it again.
Final Thought
Even when the latest Shakira headlines are quiet, there are plenty of everyday tasks that require attention. Cancelling a mandatory car insurance policy is one of them – handled correctly, it can save you both time and money.